Broadcom’s AI Moat: Credit Lines and Custom Chips
Broadcom’s AI XPV Platform links infrastructure financing to its technology, starting with a $35 billion tranche for Anthropic.
- Topic
- Market power
- Published
- Updated
- Reading time
- 6 min read

Broadcom announced the AI XPV Platform with Apollo and Blackstone on June 9, 2026. Its initial $35 billion tranche supports more than 1 gigawatt of Anthropic compute infrastructure; it is not a disclosed $10 billion OpenAI credit facility. The arrangement links financing to infrastructure using Broadcom technology. Deployment plans and future revenue remain subject to execution risk.
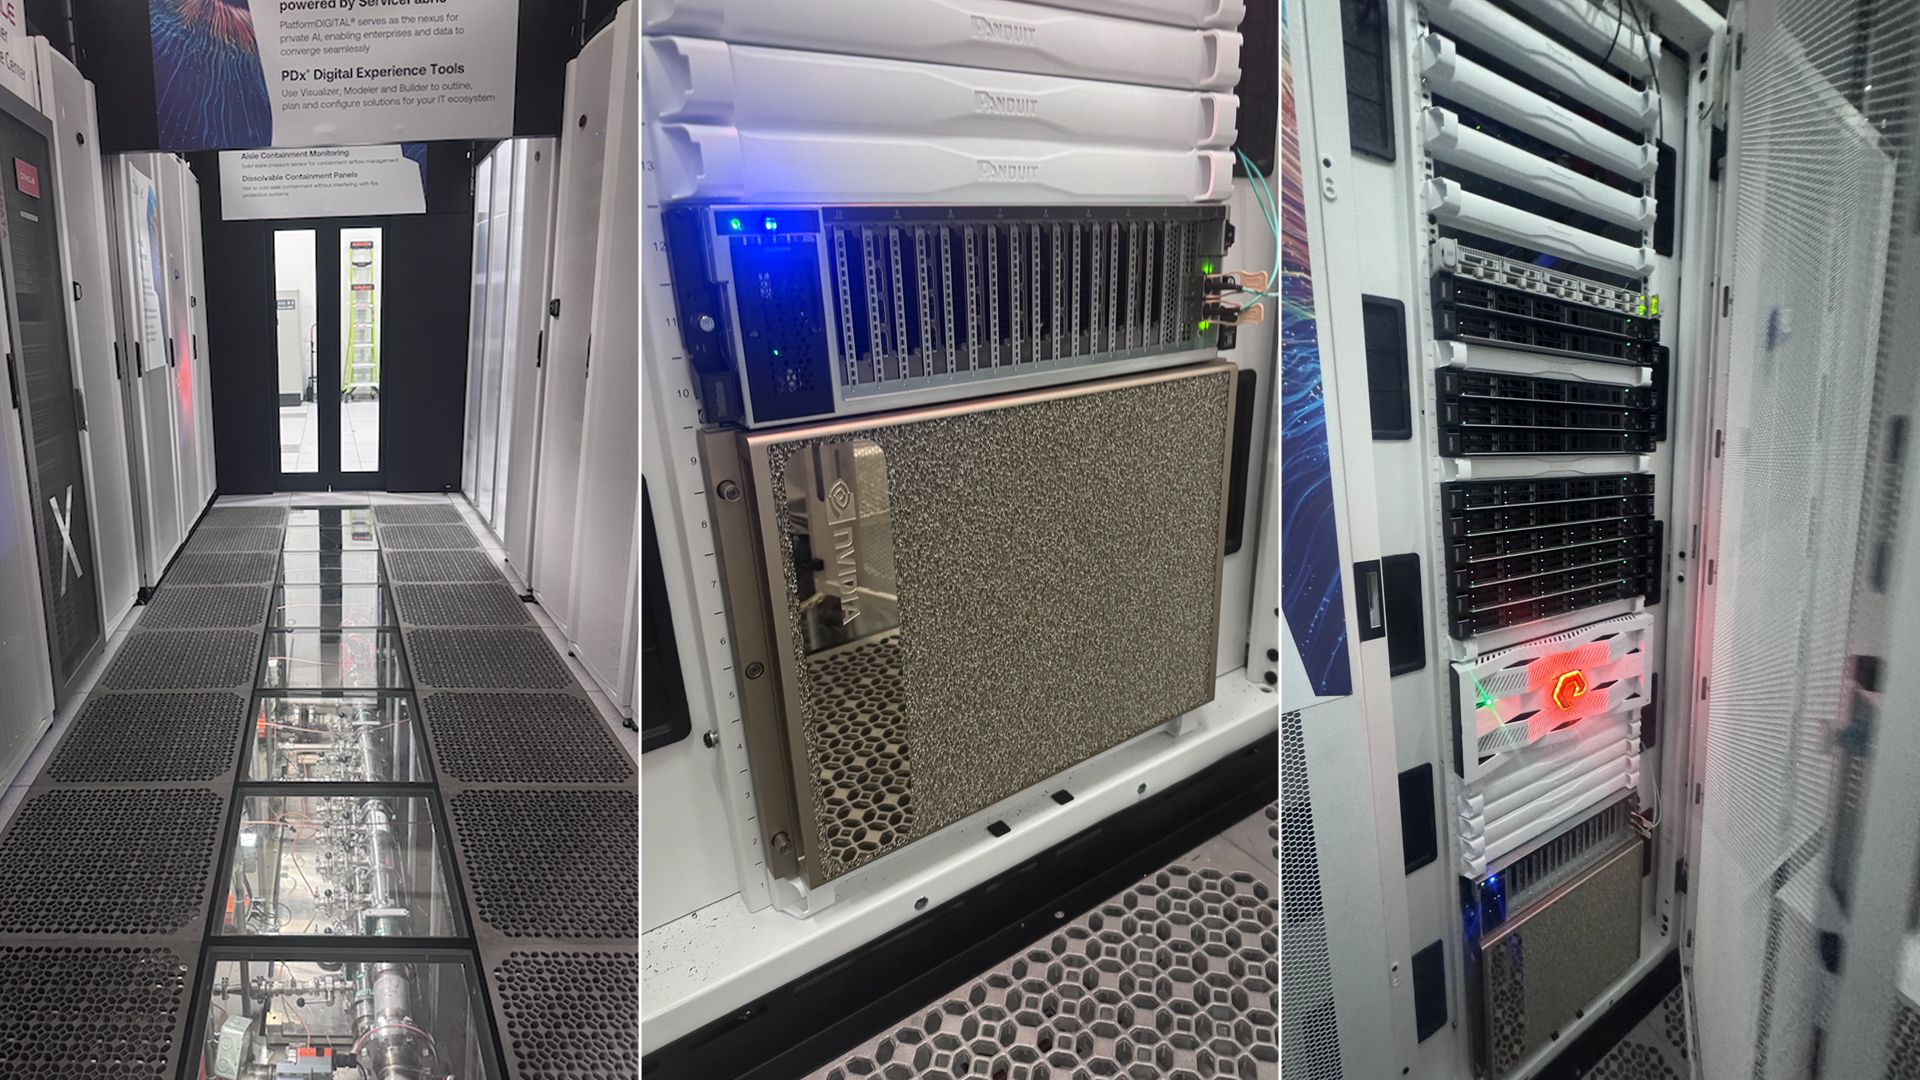
This is the new playbook for frontier AI developers. Their funding needs can exceed near-term cash flows, creating a role for infrastructure financing alongside equity capital. Broadcom, in partnership with Apollo and Blackstone, has created the AI XPV Platform, a platform intended to enable more than 20 gigawatts of compute capacity through 2028. The capital is provided by Apollo and Blackstone, while Broadcom supplies the chips and networking infrastructure. The initial transaction concerns Anthropic; the broader platform names both Anthropic and OpenAI as intended beneficiaries. The announced capacity target is not a statement that all of it has already been deployed.
Frontier AI developers face a liquidity paradox. Anthropic has submitted a confidential draft S-1, but that step does not establish an IPO date or price. Large infrastructure commitments can exceed the funding available from any single capital source.
Broadcom’s AI XPV Platform fills this void. The facility is structured to deploy capital at scale, with Apollo and Blackstone providing the funding and Broadcom supplying the necessary hardware. If the planned capacity is deployed, developers could gain access to infrastructure while Broadcom could benefit from demand for its custom silicon and networking gear. The announcement does not disclose every commercial term. Private credit could help fund infrastructure, but its benefits depend on deployment and customer economics.
This is not venture debt. It is infrastructure financing, designed to deploy capital quickly and efficiently. Private valuations alone do not establish the ability to service infrastructure commitments. Private credit may help bridge this gap, but it does not guarantee orders, completed deployments or future revenue.
Broadcom is more than a vendor—it is a strategic enabler. By arranging the financing, it aligns its interests with those of its customers. The financing could help developers build capacity and could support Broadcom hardware sales if customers deploy and use that capacity. Whether the financing creates a durable competitive advantage depends on execution and customer economics.
However, the announcement does not establish the profitability of future deployments. Apollo and Blackstone are disciplined investors, prioritizing debt returns over equity risk. If AI monetization timelines slip or private valuations contract, the economics of the AI XPV Platform could unravel. It is also worth noting that Broadcom’s largest custom silicon customers—Google, Meta, and Microsoft—do not rely on this financing. They self-fund their infrastructure needs.
Broadcom’s custom XPUs are co-designed with frontier model developers. The process is collaborative: Broadcom’s engineers work directly with customers to tailor chips to their specific workloads. The result is hardware that outperforms Nvidia’s general-purpose GPUs for the tasks that matter most to these developers.
This is a structural advantage. Switching suppliers is not just about swapping chips—it requires re-architecting entire models. The switching costs are prohibitively high. While Nvidia’s roadmap includes workload-specific optimizations, Broadcom’s co-design process creates a moat that is difficult to replicate.
However, this advantage is not invincible. AMD and Intel are investing heavily in custom silicon, and Nvidia’s next-generation GPUs may close the performance gap. Broadcom’s edge is real today, but it is not guaranteed to persist. The co-design moat is structural, not eternal.
Broadcom’s management has set an ambitious target: $230 billion in AI revenue by fiscal 2028, with earnings per share exceeding $30. These projections assume that OpenAI, Anthropic, and its four other hyperscale customers will scale their infrastructure at an unprecedented pace. They also assume Broadcom’s custom XPUs will maintain their performance edge over competitors.
The market may already be pricing in these projections. Broadcom’s stock has rallied sharply in 2024, reflecting expectations for sustained AI-driven growth. If the 2028 targets are already reflected in the current price, the upside could be limited—even if Broadcom executes flawlessly.
Investors should also consider Broadcom’s broader exposure. As a major constituent of the Invesco QQQ ETF, its performance is tied to the Nasdaq-100 and the broader mega-cap tech complex. If demand for AI infrastructure softens or Nvidia regains its footing, Broadcom’s stock could face headwinds—regardless of its private credit strategy or custom silicon moat.
Broadcom’s strategy rests on three assumptions: frontier AI developers remain ‘valuation rich,’ private credit stays available on favorable terms, and custom XPUs maintain their performance edge. If any of these fail, the moat erodes.
First, if OpenAI or Anthropic suffer severe private valuation markdowns, their ability to refinance or repay infrastructure debt could collapse. This would disrupt Broadcom’s revenue pipeline and force it to rely more heavily on self-funding hyperscalers like Google and Meta.
Second, if Apollo and Blackstone tighten credit terms or halt deployments due to macroeconomic shifts, the AI XPV Platform could stall. Private credit is not a public market—its availability depends on the discretion of institutional investors.
Finally, if Nvidia or another competitor achieves a breakthrough in workload-specific efficiency for general-purpose GPUs, the performance advantage of Broadcom’s custom XPUs could narrow—or disappear entirely. The co-design moat is structural, but it is not immune to innovation.
The platform provides a financing framework; its long-term commercial outcome remains uncertain. But investors should watch for cracks. The private credit bridge is a clever solution to a capital bottleneck, but it is not a substitute for public market liquidity. And the custom silicon moat is a competitive advantage, but it is not a guarantee of eternal dominance.
Sources
- Broadcom, Apollo, and Blackstone Establish Landmark Strategic Platform to Accelerate More Than 20 Gigawatts of Global AI Deployments — blackstone.com (primary source)
- Invesco QQQ ETF — invesco.com (primary source)
- Broadcom delivers strong earnings view as CEO touts growth with AI labs — cnbc.com
- What a Delayed OpenAI IPO Would Tell Investors — morningstar.com
- Buzz about Broadcom’s custom chips is testing, but not breaking Nvidia's dominance — cnbc.com
- Apollo, Blackstone back Anthropic's $35 billion capacity expansion in new Broadcom tie-up — reuters.com
- The Better Nvidia Killer: Broadcom or AMD? — finance.yahoo.com
Correction — 3 October 2026: Corrected the financing amount, initial beneficiary and deployment scope. The June 9 announcement describes a $35 billion initial tranche for Anthropic, not a $10 billion OpenAI facility. We withdrew adjacent and repeated assertions about OpenAI’s private valuation, annual compute spending and delayed IPO because the cited announcement does not substantiate them. The broader capacity target and potential revenue benefits are prospective, not guaranteed. We also clarified that Anthropic’s confidential filing does not establish an IPO timetable. The original publication date is unchanged. Sources: AI XPV announcement, June 9, 2026; Anthropic draft S-1 announcement.
Research briefing
Get new Monopoly MOAT research by email.
New analysis and publication updates, sent when they are published.
Discussion